
Investor relations > About us > Market environment
Market environment
The ED Invest S.A. Group operates in Poland within the property market, which remains closely linked to the country’s overall economic health. Key factors influencing the property development and construction sectors include GDP growth, inflation, interest rates, the labour market situation and government policy regarding the housing market.
According to official data from the Central Statistical Office (GUS), the Polish economy picked up pace in the second quarter of 2026 – GDP (not seasonally adjusted) grew by 3.8 per cent year-on-year in real terms, compared with 3.5% year-on-year in the first quarter, with the registered unemployment rate standing at 5.8% at the end of June (-0.3 percentage points month-on-month) and the average monthly gross wage in the enterprise sector amounting to PLN 9,395.26 (+5.3% year-on-year).
The Monetary Policy Council continued the cycle of monetary policy easing that began in May 2025, cutting the reference rate in March 2026 to 3.75 per cent – its lowest level since the second quarter of 2022. At subsequent meetings, from April to July 2026, the MPC kept rates unchanged.
Housing market
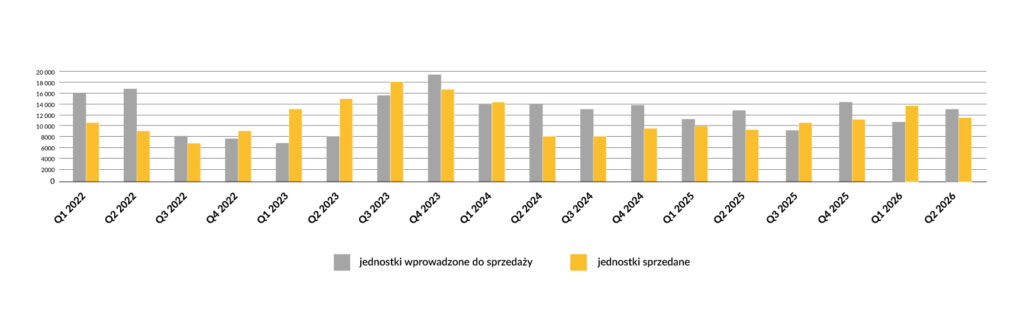
The first half of 2026 on the Polish housing market consisted of two phases. The first saw a continuation of the recovery that had begun in late 2025 and brought record sales figures – in the seven largest local markets (Warsaw, Kraków, Wrocław, the Tri-City, Poznań, Łódź and Katowice), developers sold a total of 12,900 properties, representing an increase of 11.1 per cent month-on-month and as much as 35.2 per cent year-on-year. The second quarter saw a slowdown – just over 11,800 flats were sold across the seven markets, representing a fall of 8.4% compared with Q1, although this was still 12.7% more than in the corresponding quarter a year earlier.
In the second quarter of 2026, a total of approximately 13,100 new flats were brought to market across the seven markets, i.e. 27.6 per cent more than in the previous quarter. The largest volume of new supply appeared in Warsaw, Wrocław and Kraków. As a result, the supply at the end of the first half of 2026 across the seven main markets rose to around 70,300 flats – a level close to the record figures from 2021.
Chart 1. Quarterly supply and demand report for Q2 2026 (aggregated data for seven markets: Warsaw, Kraków, Wrocław, the Tri-City, Poznań and Łódź).
Source: JLL Report: “The Residential Market in Poland | Research Poland, Q2 2026”
Availability of mortgage credit
The terms of financing for the purchase of flats remained favourable in the first half of 2026. The NBP reference rate, cut in March to 3.75 per cent (a total reduction of 2 percentage points since May 2025), remained unchanged until July 2026, whilst the 3-month WIBOR stood at between 3.9 and 4.0 per cent.
According to BIK data, the number of people applying for a mortgage in each month of the first half of 2026 was as follows: 36,600 in January, 44,500 in February, 63,300 in March (the highest figure in 18 years), 42,300 in April, 45,100 in May and 42,800 in June.
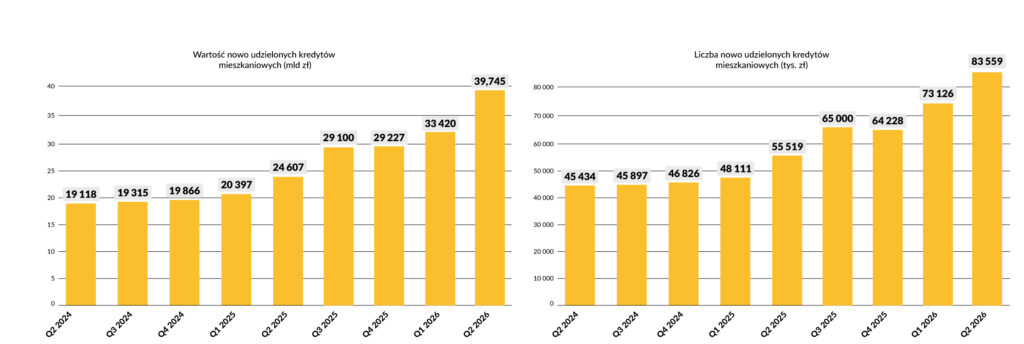
In the second quarter of 2026, banks concluded 83,559 new mortgage agreements with a total value of PLN 39.745 billion – an increase of 14.3 per cent (in number) and 18.9 per cent (in value) quarter-on-quarter, the best performance in terms of volume since 2007 and an all-time record in value in the history of the Polish mortgage market. The average value of a loan granted rose to a record PLN 475,652 (+4.0 per cent quarter-on-quarter, +7.3 per cent year-on-year).
Throughout the first half of 2026, banks granted nearly 157,000 housing loans with a total value exceeding PLN 73 billion. This was due to a decline in the balance sheet value of this portfolio following court rulings invalidating contracts, rather than a real increase in credit risk.
Chart 2. The total value and number of new mortgage loans granted in the second quarter of 2026. (in thousands).
Source: AMRON-SERFiN Report – National Report on Mortgage Loans and Property Transaction Prices No. 2/2026
Apartment prices
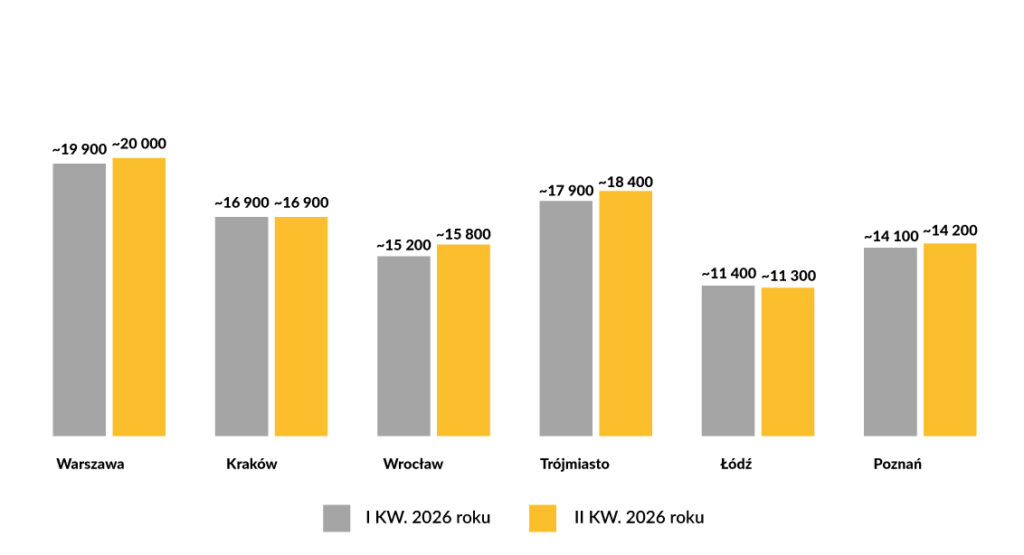
Average asking prices for flats on the primary market at the end of the second quarter of 2026 remained stable in most cities. Warsaw retained its position as the most expensive market, with a price of nearly 20,000 PLN/m² (+0.5% month-on-month, +6.9% year-on-year), whilst Łódź remained the cheapest, at 11,300 PLN/m² (-0.9% month-on-month). The other markets recorded the following asking prices: the Tri-City at 18,400 PLN/m² (+2.8% month-on-month), Kraków PLN 16,9 thousand/m² (unchanged), Wrocław PLN 15,8 thousand/m² (+3.9% month-on-month), Poznań PLN 14,2 thousand/m² (+0.7% month-on-month) and Katowice PLN 12,7 thousand/m² (unchanged).
It should be borne in mind that asking prices still differ significantly from transaction prices – in most cases, buyers can expect substantial discounts on the list price, and this situation is likely to continue until the end of 2026.
This is confirmed by average transaction prices (as recorded in notarial deeds and bank valuations). In the second quarter of 2026, the highest transaction price per square metre of flat was recorded in Warsaw – 15,707 PLN (+4.0% quarter-on-quarter, +6.4% year-on-year). The next highest prices were recorded in Kraków – PLN 14,264 (+2.2% year-on-year), Gdańsk – PLN 12,803 (the highest annual growth rate among major cities: +7.5% y/y), Wrocław – PLN 11,812, Poznań – PLN 10,555 (+2.0% y/y) and Łódź – PLN 8,103 (+2.1% y/y). The situation in Wrocław is particularly interesting, where – in contrast to rising asking prices for new flats (JLL data) – the average transaction price was 2.9 per cent lower than a year earlier, which further confirms the growing discrepancy between developers’ price lists and the actual negotiated sale prices.
Chart 2. Average prices of flats on the primary market in Q2 2026 (in PLN/m², inclusive of VAT, in developer-finished standard).
Source: JLL Report: “The Residential Market in Poland | Research Poland, Q2 2026”
Developer activity – demand vs. supply
In Warsaw alone, 3,840 new flats were sold in the second quarter of 2026 – 9.4 per cent fewer than in the previous quarter, but still 4.6 per cent above the average quarterly sales figure for the last five years (3,670 flats). Developers responded by increasing supply – they brought 4,753 flats onto the market, i.e. 66.8% more than in the previous quarter. As a result, the supply at the end of June 2026 rose to 16,345 flats available on the market (+7.1% quarter-on-quarter).
The sharpest decline in sales was recorded in Warsaw (-16.5%) and Łódź (-26.2%); Wrocław, Poznań and Katowice recorded slightly weaker results, whilst the decline in the Tri-City was negligible. Kraków proved to be a positive exception, with sales rising by 13.6%.
Institutional investors operating in the rental housing segment (PRS) are also playing an increasingly significant role in the Polish housing market.
According to CBRE data, in June 2026 such investors owned over 32,000 rental flats in Poland, with a further 15,400 units in the planning stage or under construction. Warsaw remains the largest local PRS market, with nearly 10,900 flats in operation and a further 8,500 in the pipeline.
It is worth noting here that cost pressures in the construction sector are increasingly being driven by rising prices of steel and concrete, as well as wages for skilled workers – in May 2026, the construction and installation output price index for the building construction category rose by 5.2% year-on-year. Despite this, in the second quarter, developers commenced construction of 38,700 flats (+25.4% quarter-on-quarter, +21.8% year-on-year), whilst the number of planning permissions rose to 48,900 units (+39.2% year-on-year), remaining well above the number of projects commenced.
Forecasted changes
The baseline scenario for the second half of 2026 assumes that inflation and interest rates will remain at 3.75 per cent until the end of the year, with a possible further cut at the turn of 2026/2027. The NBP’s July 2026 forecast predicts GDP growth of 3.3 per cent in 2026 and 3.0 per cent in 2027. Demand for credit is expected to stabilise at a high level, whilst cost pressures in the construction sector are set to persist, which may translate into higher prices for new developments in 2027.
No new government schemes to support demand for flats are expected by the end of 2026, although work is underway on a bill aimed at increasing the availability of land for new developments.
Buyers’ behaviour will be increasingly shaped by selectivity and a willingness to negotiate, the growing importance of energy efficiency in buildings, and a preference for ready-to-move-in flats amid geopolitical uncertainty.
Developers will continue their policy of carefully matching new supply to demand in individual local markets, limiting over-supply where it remains too high – particularly in Łódź and Katowice. They will speed up the completion of previously prepared projects, although, given the persistently high supply of ready-to-move-in flats, companies are pursuing a selective investment policy, focusing on projects with the highest sales potential.
A key source of uncertainty for the second half of the year remains the development of the geopolitical situation, including the further course of the war in the Persian Gulf – its impact on inflation, the cost of finance and buyer sentiment will require ongoing monitoring.